‘The mind boggles’: federal envoy blasts NT housing decision
Posted on 14 Oct 2026
The federal government’s special envoy for social housing and homelessness, Josh Burns MP, has…
Posted on 14 Oct 2026
By Nick Place, journalist, Community Directors
The Reserve Bank’s move to ban card payment surcharges has led to complications for charities and not-for-profits who rely on donations, with some organisations unclear whether they need to absorb transaction costs formerly borne by donors.
The sector appears confused by the change and how to deal with it, and EP Law, a legal offshoot of Equitable Philanthropy, has held more than 60 conversations in the past week alone with charities seeking guidance.
“Our charity partners and even the broader sector were getting in touch with us saying, ‘Do you know what's going on with this?’ Charities are really eager to get it right,” said EP Law’s Kirstie Le Lievre. “Some of them have already had queries from their donors saying, what does this mean for you? And charities have come to us eager for some practical guidance on how to get it right.”
The dilemma for charities is how to stop the change affecting their bottom line, she said. “Charities don't want to be left out of pocket by the new rules, and donors understand as well that costs matter. There’s an understanding that everything does cost a bit more now and charities do have costs as part of their operations.”
Charities need to be upfront with donors, so there is no erosion of trust through murkiness over who is paying the fee and how, she said.
One obvious solution would be for credit card platforms to charge a zero per cent card processing fee on donations. Visa already does this, and EP Law said it would encourage the other card networks to work with banks and payment providers to do likewise, or to charge as close to zero as possible.
Another option is for charities to openly invite donors to donate a little extra to cover operational costs, as an opt-in rather than the previous opt-out, and for larger charities to use the muscle of their transactional volumes to push banks and payment providers to lower fees.
“Within the breakdown of platform fees, there is a part that is negotiable,” Le Lievre said. “It will be fascinating to see from a commercial perspective whether that does start to shift and we start to see some of the other platforms offering a better deal, so to speak, to charities.
The impact of the surcharge removal will be considerable for some organisations. Le Lievre said one charity partner that raised $2 million in donations with a major Christmas appeal last year attracted $40,000 in surcharges, which roughly 85 per cent of donors (11,500 donors) chose to cover via a “tip jar” feature.
An issue for the charity sector is that its regulators have not issued guidance on what are acceptable ways for charities to pass transaction costs on to donors.
“We’ve given some advice around the fact that charities can present to their donors to help cover operational costs,” Le Lievre said. “But until we get any further guidance from the ACCC [Australian Competition and Consumer Commission] and from the different fundraising bodies across Australia, like Consumer Affairs throughout the jurisdictions, we need to get clarity from the platforms themselves around what's exactly compliant with the terms of their agreements.”
“It is a new cost at a difficult time, which is why we encourage a sector conversation with the card networks.”
Previously, a charity was able to process a donation with the surcharge clearly stated, but now if a donor donates $100, the actual charge must be $100.
Equitable Philanthropy’s Catherine Brooks said the thinking behind the surcharge removal was good. “If I go to a cafe and buy a coffee for $5, it’s annoying if the actual charge is $5.70,” she said. “I understand the concept of transparency. I think what we just didn’t appreciate until our charity partners raised it is this impact on charities.
“There are obviously workarounds, but what we’re recommending is people need to speak to their platform provider and they also need to see if they can speak to their bank around reducing the cost for the charity. In the interim, we will also write to the ACCC seeking guidance from them so that can continue to update the sector.”
Brooks added that GiveNow was one donations platform that had provided clear information about the changes on its site to help charities and donors. Others needed to follow suit, she said. (GiveNow is a sister company of Community Directors)
Le Lievre said she believed regulators would realise they needed to provide clarity on what charities are allowed to do.
“I suspect that we will get some guidance from the ACCC, but we'll have to, because I think there’ll be enough queries from donors going, ‘Why am I being invited to give a little bit more? How is this not the credit card surcharge that’s supposedly gone?’
“I think that there’s got to be some guidance and coaching around the right level of wording that charities need to share with their donor communities. There’s been so much confusion on that point.”
EP Law has released a summary of its conversations and observations on the issue so far, including the following answers to common questions:
Can charities still ask donors to help cover costs?
Yes. What they cannot do is add a fee because a donor pays by card. A genuine, optional extra gift, offered the same way however the donor pays, is a different thing.
Will the ACCC take action against charities?
The ACCC does not enforce the card networks' rules. It does enforce consumer law, and has warned against renaming a surcharge as another fee. For charities, the bigger issue is donor trust: being upfront is right whatever the enforcement risk.
What about platform tips on giving sites?
A contribution that funds the platform and does not depend on how the donor pays is not a card surcharge, but best practice is still opt-in.
Is this going to cost charities money?
For many, yes. A handful already built card costs into their budgets. For the rest, it is a new cost at a difficult time, which is why we encourage a sector conversation with the card networks.
EP Law has also outlined where danger lies if a charity mishandles the new rules:
Enforcement is contractual.
The ACCC states that card networks and payment service providers, not the ACCC, are responsible for enforcing the no-surcharge rules. A breach is most likely to be dealt with by your provider. It might direct you to remove the fee or change your merchant terms, In serious cases, it might suspend card acceptance.
The ACCC still has a role.
The ACCC has warned that trying to avoid the ban by describing a card surcharge as another type of fee may be misleading conduct under the Australian Consumer Law. This is the main legal risk for any arrangement that looks like a surcharge under another name.
The old cost-based defence has gone.
Until 1 October 2026, a surcharge was lawful if it did not exceed the charity's cost of accepting a card payment. Those rules ended on that date. You can no longer defend a card-linked fee by saying it only recovers what you are charged.
A legislated ban remains possible.
The RBA has said that if surcharging continues, it could recommend that the government legislate a ban. Arrangements that test the edges of the rules are likely to attract attention.
EP Law can be contacted here.
Posted on 14 Oct 2026
The federal government’s special envoy for social housing and homelessness, Josh Burns MP, has…
Posted on 14 Oct 2026
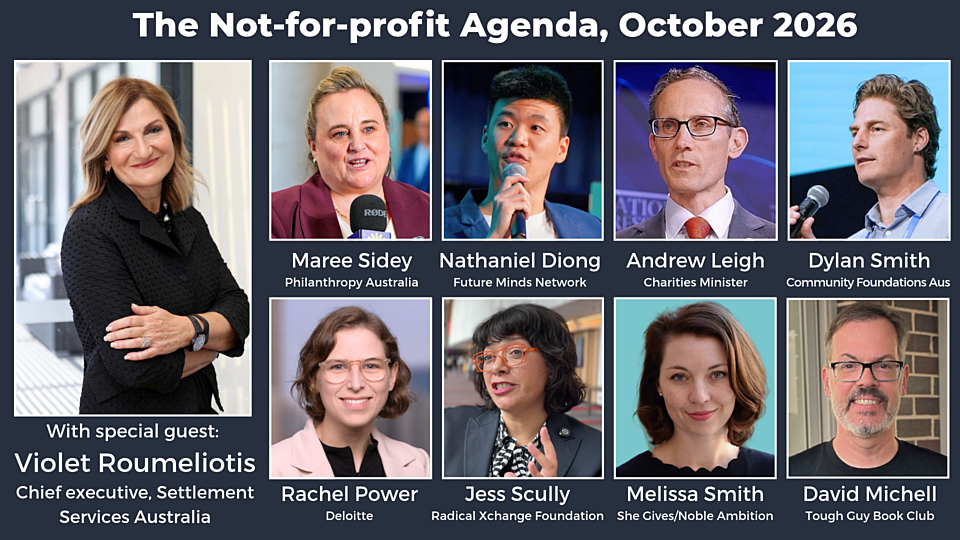
A special guest with her finger on the pulse of one of the biggest issues facing Australia –…
Posted on 07 Oct 2026
A major public campaign launched this morning is calling on the federal government to restore…
Posted on 07 Oct 2026
The Australian Literacy & Numeracy Foundation (ALNF) has announced a partnership with mining…
Posted on 07 Oct 2026
A conference in Darwin will this morning hear detailed, strategic plans for how Australia could…
Posted on 30 Sep 2026
Not-for-profit leaders have been warned to be wary of approaches from potential “funding partners”…
Posted on 30 Sep 2026
More than 200 fully funded Centre for Social Impact (CSI) scholarships will help equip for-purpose…
Posted on 30 Sep 2026
Personal stories are among the most powerful tools a charity can have to raise funds and awareness,…
Posted on 23 Sep 2026
A just-released major global survey of charities has found that demand for charity assistance has…
Posted on 23 Sep 2026
Fresh from welcoming delegates to last week’s Philanthropy Australia conference in Brisbane,…
Posted on 23 Sep 2026
A national strategy to develop Australia's regional cities is needed to break the housing…
Posted on 23 Sep 2026
Eight years after a report to Treasury first suggested the charities regulator should be more…